

This article is written for those of us who come from backgrounds where "wealth" wasn't part of the vocabulary. It's a wealth-building summary based on six years of lessons I've learned trying to invest in property.
Let's be honest. Due to South Africa's sketchy past—a machine designed to create a permanent poverty trap for the majority—most people are systemically excluded from the property market. Recent Stats SA data shows a median household income of less than R8,000 a month. The cold reality is that for most, the entry ticket is impossibly high. I acknowledge that.
But for those of us who have, perhaps by luck, crossed that first affordability line, there's a second, invisible barrier: a gap in "financial street smarts". I know this barrier well. I recall being faced with my first property purchase in 2012. The numbers felt so big and the process so overwhelming that I backed out. It was one of the biggest mistakes of my life.
When I eventually did buy one, I went in with the typical mindset most of us were taught: the goal is to buy a home and pay it off. I've since learned that's not a wealth-building strategy.
My realization now is that buying your first property isn't the goal; it's the start. It’s the process of acquiring a tool. This guide is my two-part framework: Part 1 is how to get the tool. Part 2 is how to actually use it.
Part 1: Getting in the Door (My "How-To" Guide)
This is the bureaucratic, painful part, and here is my survival guide for the stages that matter most.
1. The Prep: My Goal, My Horizon, and My Maths
Before I talk to anyone, my preparation starts as a long-term, personal process. It begins with setting a clear Goal. You must have one. While a goal like "I want a home for my family," is a really good want, I like to find something more tangible: What quality of life do I want to live in X amount of years?. How much will I need to fund that quality of life?. This gives me an end state to work backward from, and that becomes my plan.
Alongside this, I like to set a "readiness horizon". This isn't a vague date; it's a timeline, often lasting up to 3 years, dictated by the single most important factor: available cash flow. I can now ask the specific question: “How much cash can I build in X amount of time, and what value of property will that afford me?”
Once I have my "why" (the goal), "when" (the horizon), and sense of “how much” (budget), I can start constant "window shopping". Even when I'm not in a position to buy, I'm looking in my areas of interest, doing calculations, and checking affordability. This is my research. This is my first line of defense. This is how, by the time my readiness window finally opens, I already have a deep sense of my listing price, interest rate expectations, and the market.
This constant research then feeds my own maths. I don't rely on basic affordability calculators. I take those numbers, put them in my own spreadsheet and host of AI Agents, dashboard and calculators along with my other data points—salaries, expenses, etc.. I run three scenarios: Worst-case, 'It Can Work', and Brilliant, based on purchase price, interest, and income projections. I always budget on the least optimistic projection.
This entire process does two things: it builds my "financial street smarts," and it gives me a rock-solid, data-backed plan before an estate agent ever tries to sweet-talk me.
2. The Search: Field Work
You must do fieldwork. I spend months scouring property sites, but I now understand that what I see online is a fantasy. I look at hundreds of properties online and filter them down to several dozen to visit in person.
Every property has a smell; for some, that means "run away," for others, it's an opportunity. When I went to Obs Court, for instance, every single floor smelled like a college dormitory, fitting its student demographic—not the kind of tenant I want. 1 Albert was selling studios for dirt cheap, but every floor smelled of wet cigarette and marijuana, with loads of shady characters around. As the Agent put it, “look this is where most guys park their side chicks”. I'm sure as hell not spending a bar on a secret love nest, and not where I'm looking for stable tenants.
Even seemingly better-quality buildings like Wex 1 and Foreshore, it was clear they were set up for Aparthotels. That's a segment I'm not looking to compete in, and I certainly don't want to be sharing 30% of my revenue with TotalStay. I only get this "ground truth" by doing the fieldwork.
3. The Loan: Finding a Partner, Not a Bank
This is critical. My hard-won lesson is that all banks are not equal. Most of us start with consumer banking or bond originators, again perfectly OK if this is your 1st purchase. But you are going to get cookie-cutter offers with zero wiggle room, and it's not a great path to sub-prime lending, which is what you want. The option “private banking” with consumer banks, which is often just a slightly better cookie-cutter.
Don’t get me wrong, Nedbank gave me rates, and their customer service really great, a good launch pad to help me start, but they ran out of steam quickly. I had no luck in materially adjusting my rates as my financial position moved, and even less luck when trying to explore better structures for my lending and other investment activities. And to be fair, this could just be ignorance on my part; knowing what I know now, I might go into a relationship with them pressing for different things.
And this is why finding the right lending partner is important, and what changed when I moved to a real lending partner like Investec. They looked at my whole portfolio, understood my goals. They didn't discourage me from buying in an LLC—in fact, they helped me find consultants to advise on structures. I now look for a partner who understands my long-term wealth-building plan, not a clerk who can only process a standard bond.
4. The Admin: The Sale
Once I've signed the Offer to Purchase (OTP), the real admin burden begins. It reminds me of that scene in Jupiter Ascending showing the mind-bending bureaucracy when they go to the Commonwealth Ministry to claim a Title for the dubious house of Abrasax. Jupiter and her AI were bounced around departments and eventually had to resort to bribery to get the title.
Luckily we don’t have to resort to bribery, but this is where you'll deal with banks, agents, sellers, SARS, and two sets of attorneys (bond and transfer). They will all ask you for the same FICA documents multiple times. This part is a 3-month marathon from OTP to getting the keys. You just have to endure it. It's the price of entry.
5. Busting the Myths That Stop You

Before we get to the meat, I want to address a few myths that hold people back.
- Myth 1: The "Build Your Credit" TrapI have to address a damaging misconception: the idea that you need to "build a credit record". This usually translates to taking on more credit, like clothing store accounts, thinking it makes you more attractive to a bank. Kak man! Do not fall into this trap. All that does is increase your liability and reduce your income—which is what the banks actually look at. Unsecured debt does not give you a good credit record.
- Myth 2: "Affordability" is the Only BarrierWhile your bank-approved "affordability" is the main and primary barrier to entry, your available cash flow is what will very quickly pump the brakes on your investment aspirations. I was not prepared for the shock of Transfer & Bond costs on my first purchase. Hypothetically, even if a bank told me I could get a bond for R3 million, it's meaningless. I wouldn't have enough available cash to cover the enormous transfer and bond fees for that amount. Your "affordability" on paper is useless without the cash to cover the costs, which can easily be R100,000 for an entry-level investment property, and that might exclude a mandatory deposit if it applies.
- Myth 3: "Property Always Appreciates"The reality is that most properties are not investment grade. We're all taught that property values always appreciate, but people forget our old friend: inflation, which runs at 4%-6% per annum. This is an issue with the time value of money. You might buy a property for R1M and in 10 years it's worth R1.2M, but in reality, that R1.2M at the end of the term is worth less than the R1M you already spent. You've actually lost money. This can be made even worse if you have a bad interest rate—it's like a double whammy.
Part 2: The Real Goal: The Engine
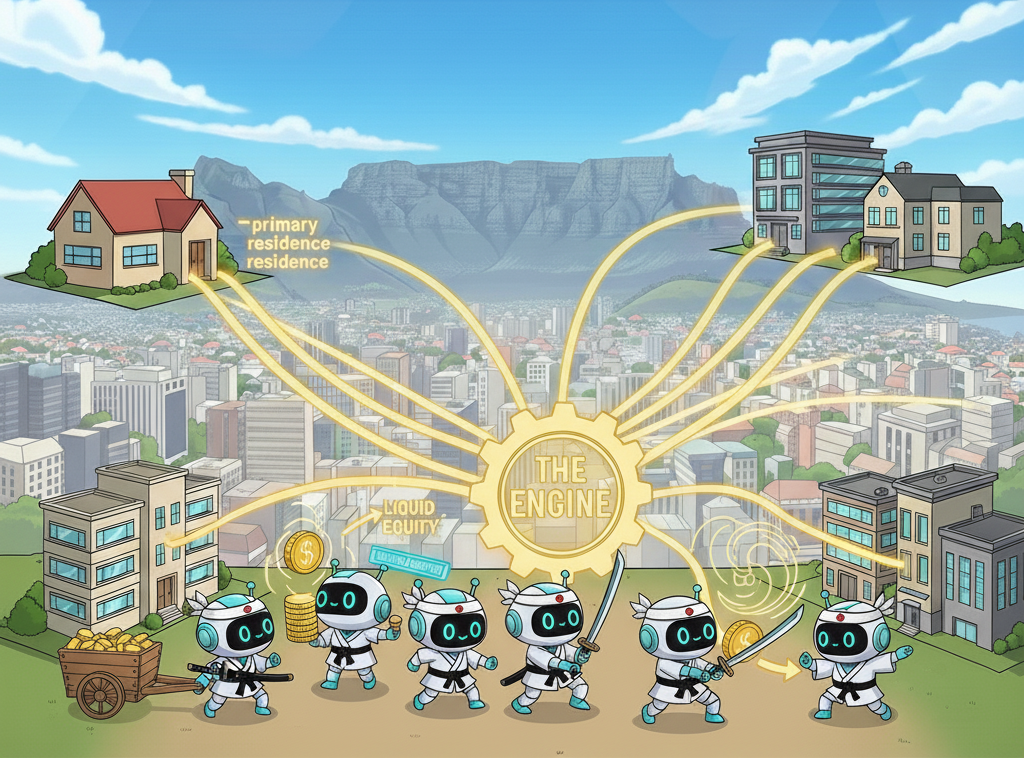
This is the main event. Going through Part 1 is just the entry ticket.
Now that we've busted the myth that just "owning property" makes you wealthy, we can talk about strategy. Most people buy their home, breathe a sigh of relief, and then just... pay it off. This is Path A.
And let's be clear: that is perfectly okay. You're right. Family life is tough, and priorities change, especially when you have kids. Or maybe you just don't have this kind of appetite for risk. Path A is a valid and safe path that prioritizes security.
The strategy I'm documenting here is Path B: Leveraging Jiu-Jitsu. This isn't the only way; it's just an alternative path for those who, like me, have the risk appetite and want to actively use their equity to acquire more assets.
| Feature | Path A: The "Security" Way (Pay off Bond) | Path B: Leveraging Jiu-Jitsu |
| Primary Goal | Get rid of debt. Prioritize security. | Use equity to acquire more assets. |
| My Extra R2,000/mo | Goes to Principal to shorten the loan. | Goes into an Access Bond facility. |
| My Equity | LOCKED. It's secure but not liquid. | LIQUID. It's available cash I can withdraw. |
| The Result | I own 1 secure property with a smaller bond. | I own 1 property... and am funding my 2nd. |
This is the "street smart" that bridges the wealth gap if you choose to take this path. Here is the 5-step recipe I follow.
My 5-Step Wealth Recipe
Step A: Get the Right Tool.
I make sure my primary bond is an "access bond" or "flexi facility". This allows me to withdraw any extra money I've paid into it.
Step B: Build Liquid Equity.
I have to be disciplined. I pay extra cash (e.g., R2,000/month) into this bond. This builds a liquid buffer I can withdraw at any time.
Step C: Find My Target.
After 2-3 years, I'll have a significant cash buffer (from my extra payments) sitting in my bond. I can now go to the bank, show them the property's appreciation, and ask for a facility extension. Between my buffer and the extension, I now have the cash to fund the deposit and transfer costs for my second property.
Step D: Attack the New Bond.
I use my leftover cash, my annual tax return (which I now get from my new rental property), and my continued monthly surplus to "smash" the new property's bond.
Step E: Reach Cash-Flow Positive.
My goal is to get the new property's rental income to cover all its own costs (bond, levies, rates) within 2-3 years. Here’s how that looks on a new R1.5M flat I've modeled:
| Metric | Year 1 (Start) | Year 2 (Start) | Year 3 (Start) |
| Rental Income | R 13,000 | R 13,650 (+5%) | R 14,332 (+5%) |
| Total Expenses | R 14,300 | R 13,715 | R 13,335 |
| MONTHLY CASH FLOW | - R 1,300 | - R 65 | + R 997 |
| Cash Injected (This Year) | R 84,000 | R 49,000 | R 44,000 |
As you can see, by the start of Year 3, the property is paying for itself. The "deficit" was just a short-term investment I had to plan for.
Part 3: Finding the Right Tenant
Securing a reliable occupant is the most critical step in this journey. Most rental agencies will ask for 8% to 10% of your monthly income to manage the process, which often feels like a high price for a relatively simple service. I personally use Preferental; they charge a much more manageable 2% fee. You should expect to pay placement costs, and it has become standard practice for applicants to cover their own background check fees as well.
Whatever you do, I do not advise doing the vetting yourself. The process is incredibly labor-intensive and can be emotionally draining to navigate on your own.
The Reality of Financial Health
When you start the search, you will encounter many individuals facing difficult circumstances. It is genuinely sad to see how many in our country are locked in a cycle of debt, often relying on multiple micro-loans just to get by.
It is natural to feel for them, but as an investor, you must remain objective. In the past, I’ve tried to make special provisions to help those who were struggling to cover their monthly costs. This often makes the situation harder for everyone involved; if a person has a compromised financial history, it becomes very difficult for them to move on later because other property owners may not be willing to take the risk. For the long-term success of your investment, finding someone with a solid, proven track record is the most important thing you can do.
Managing Inherited Residents
Sometimes you will buy a property that is already occupied. You need to be aware that this carries a level of uncertainty. My first purchase came with a leaseholder whose financial situation was far more unstable than I realized at the time, which created a lot of stress.
I took a similar risk with my Woodstock property, but I felt more comfortable there because the high demand in that area provided a safety net. However, if you are at all unsure about the existing arrangements, make it a condition of the sale that the property is delivered vacant. This gives the current occupants sufficient time to find a new home and allows you to start the relationship with a fresh, vetted placement.
The High-Demand Buffer
If you’ve bought in a popular area, your unit likely won’t stay empty for more than a month. Use that knowledge to stay patient and thorough. It is much better to have a vacancy for 30 days while you find the right fit than to rush into a lease agreement that doesn't quite meet your requirements.
Conclusion: The Real Tool is Education
While this is not for everyone, it’s certainly not just for millionaires. If you have a Bond Primary residence, then you can start putting it to work today. This has been a 6-year process of proving to myself that I can use the home I live in as the engine to buy my next asset, and exponentially grow in the years to come, and I’m still checking daily that my projections are panning out, not out of anxiety but sheer excitement having seen the growth.
This process is confusing, and everyone's path is different. But the real tool here is education and financial literacy. Just start. Honestly you'll figure it out.
PS: This article does not constitute financial advise, tax and property purchases are complex always seek professional help